Fixed Income Outlook 4Q 2026
Key Takeaways
Actively Navigating the Rising Rate Environment
Stronger AI-fueled growth expectations, rising inflation and the Fed’s hawkish shift have propelled yields higher in the past quarter. They currently sit at attractive levels, however a sustained fixed income rally may require lower energy prices or slowing growth momentum. The rates landscape remains highly regional however, allowing investors to exploit mispricing when local market fears become overextended.
The US dollar could benefit from positive tailwinds with a more hawkish Fed having started a hiking cycle, particularly if global energy prices move materially higher. By contrast, lower energy prices may not lead to large dollar weakness as rate expectations in the rest of the world move lower more significantly than in the US.
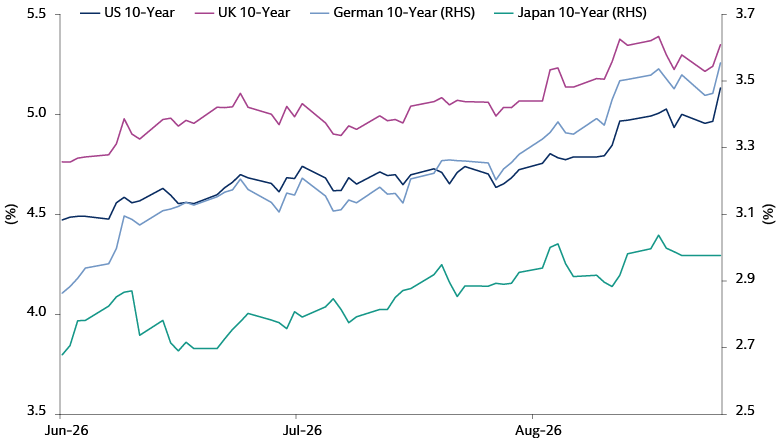
Source: Bloomberg, Goldman Sachs Asset Management. As of September 23, 2026.
The Next Stage for AI Financing and Credit Markets
The toolkit being used to fund the AI buildout is continuing to expand, with chip-backed financing being the latest in a series of novel funding structures. We still see AI as a secular growth story with a long way to run in terms of both its buildout and ability to generate returns. However, we remain vigilant to new and emerging credit risks that can arise.
In credit markets more broadly, extremely tight spreads combined with a backdrop of higher rates and energy prices warrant caution. This could include moving up in credit quality to avoid issuers potentially vulnerable to ‘higher-for-longer’ scenarios; however, the resilient global growth picture could present a buying opportunity on any meaningful pullbacks.
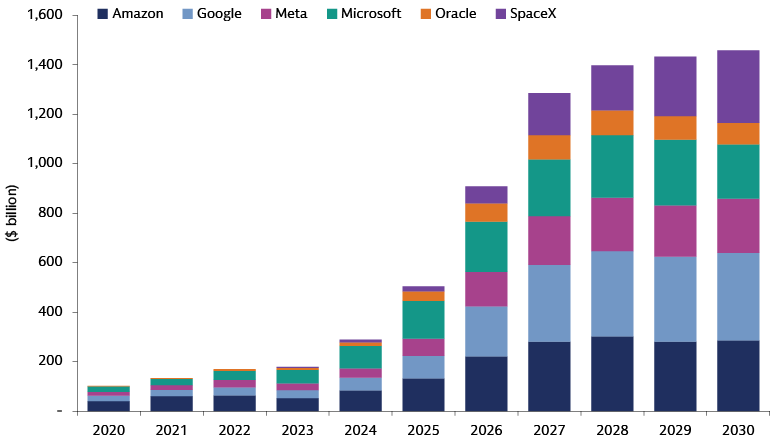
Source: Barclays, Goldman Sachs Asset Management. As of September 2026.
Key Investment Ideas
Active Selection: AI buildout and adoption is creating multiple opportunities across fixed income markets; as well as potential pitfalls. With the AI buildout developing so quickly, we prioritize where we believe we are being appropriately compensated for risk across securitized and investment grade credit markets.
Diversification: Yields are at levels where they can add value in scenarios where strong nominal growth slows, particularly with elevated risk-asset valuations and uncertainty. Core government bonds and high-quality credit should have a part to play.
Income Generation: We believe higher real yields have created one of the most appealing carry environments in recent years. We see opportunities across the fixed income spectrum, particularly in emerging markets.
Download the full PDF for our easy-to-read Sector Allocation: Key Exposures and Quarterly Changes on positioning across sovereign bonds, currencies, and spread sectors.