2026 Global Alternatives Survey: The LP View
Key Findings
Constructive But Selective
Despite geopolitical uncertainty, inflation concerns and liquidity constraints, institutional investors remain committed to private markets. Most respondents view opportunities across private equity, private credit and infrastructure as equal to or better than last year, and more than a third expect to deploy more capital. As a result, investors are not retreating from private markets, but becoming more selective in how they allocate capital, manage liquidity and choose investment managers.
Reshaping the Landscape
Many remain under allocated to private markets, particularly private credit and infrastructure, suggesting continued room for capital deployment. While slower distributions continue to constrain new commitments, investor appetite remains resilient. In response, investors are placing greater emphasis on liquidity management, with secondaries and co-investments becoming increasingly important components of portfolio construction.
Manager Selection in the Age of AI
Manager quality remains a key driver of capital allocation decisions, with investors increasingly focused on underwriting discipline, specialist expertise and differentiated investment approaches. At the same time, respondents identified artificial intelligence as the leading force expected to reshape the private markets industry over the next five years. Together, these trends suggest investors are raising the bar for manager selection, seeking firms with both proven investment capabilities and the ability to adapt to structural changes across private markets.
Rethinking, Not Retreating
What risks are top of mind for LPs in 2026?
For the third consecutive year, geopolitics ranks as the leading investment risk. Geopolitical tensions were ranked among the top five risks by 82% of respondents, followed by inflation at 67% and the risk of an economic slowdown or recession in the US at 63%.
What do you believe are the greatest investment risks today?
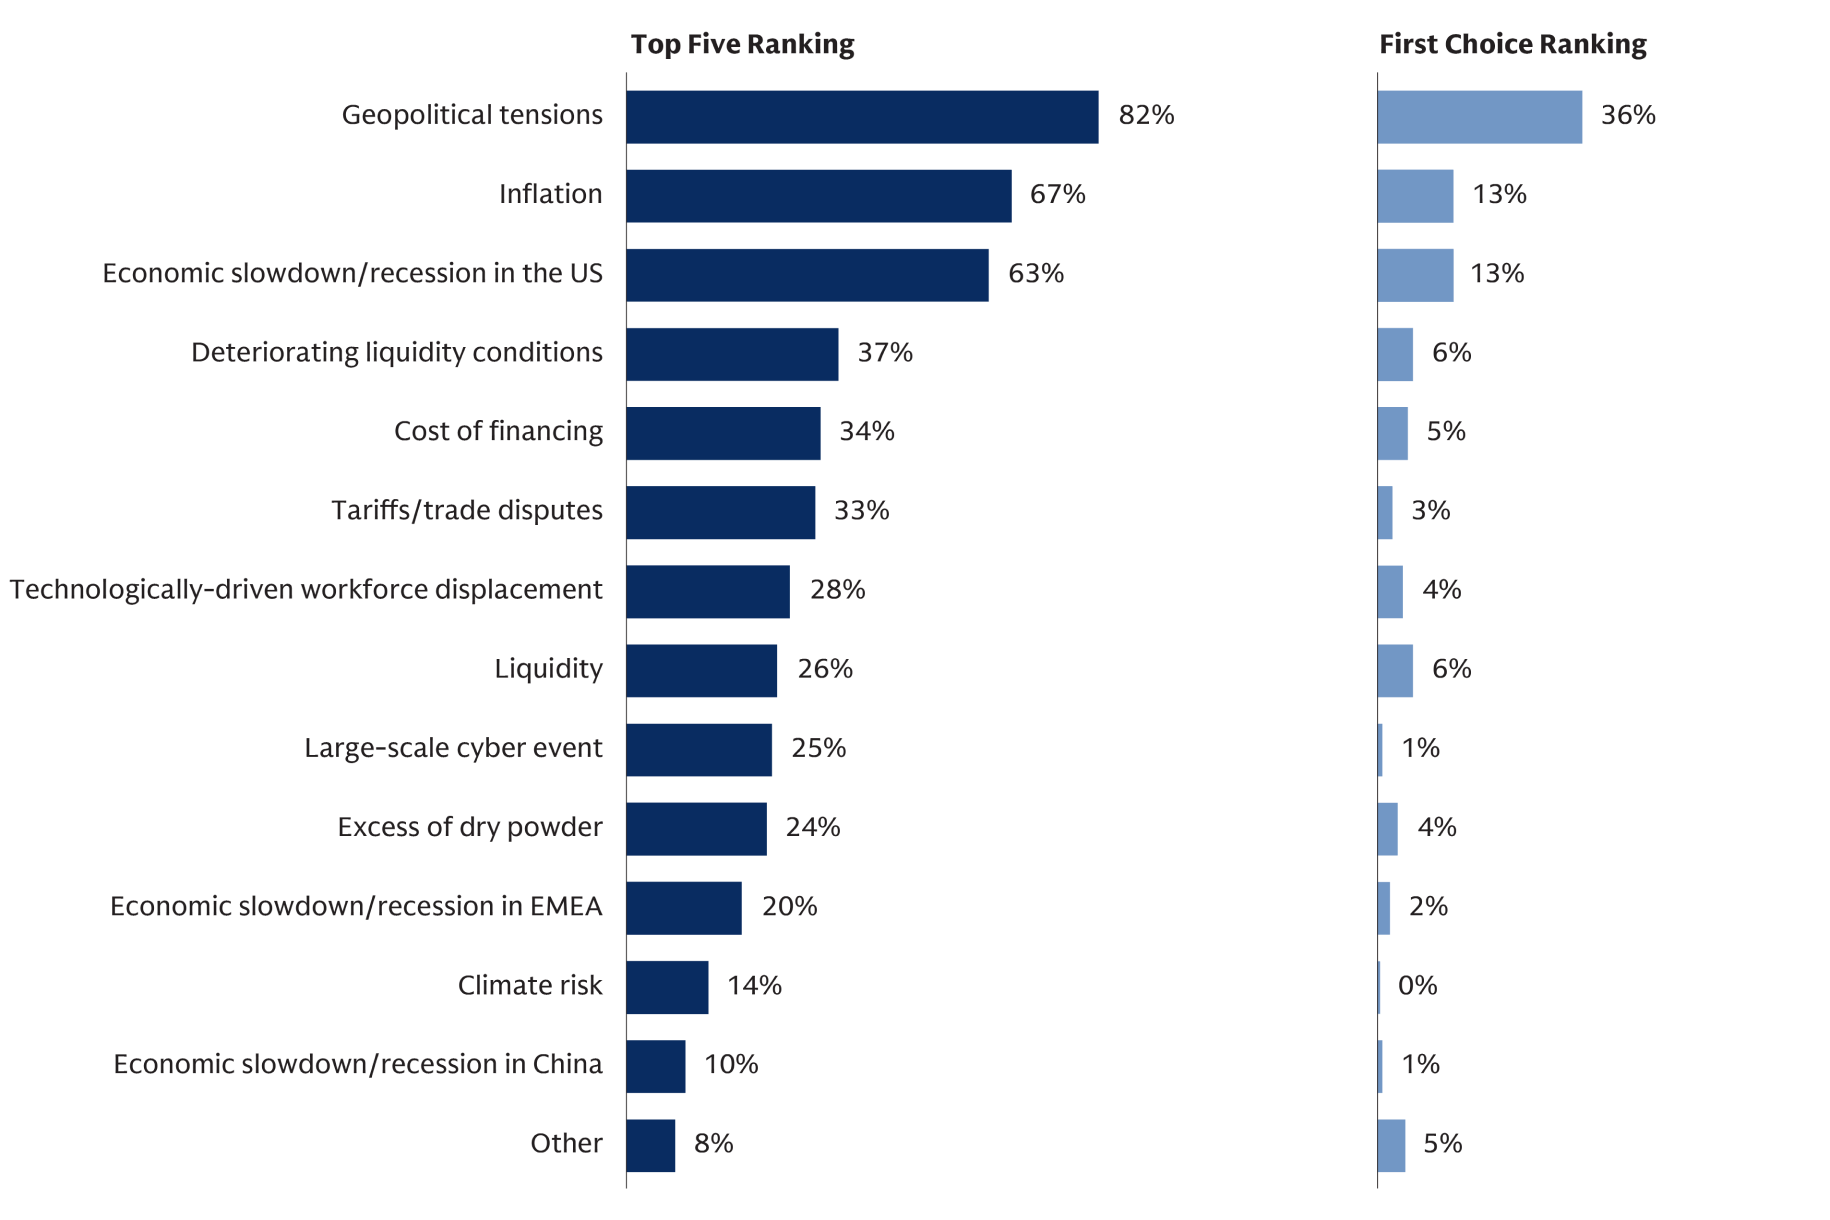
1 Showing first choice rankings
Deployment intentions remain steady, but distributions are the constraint
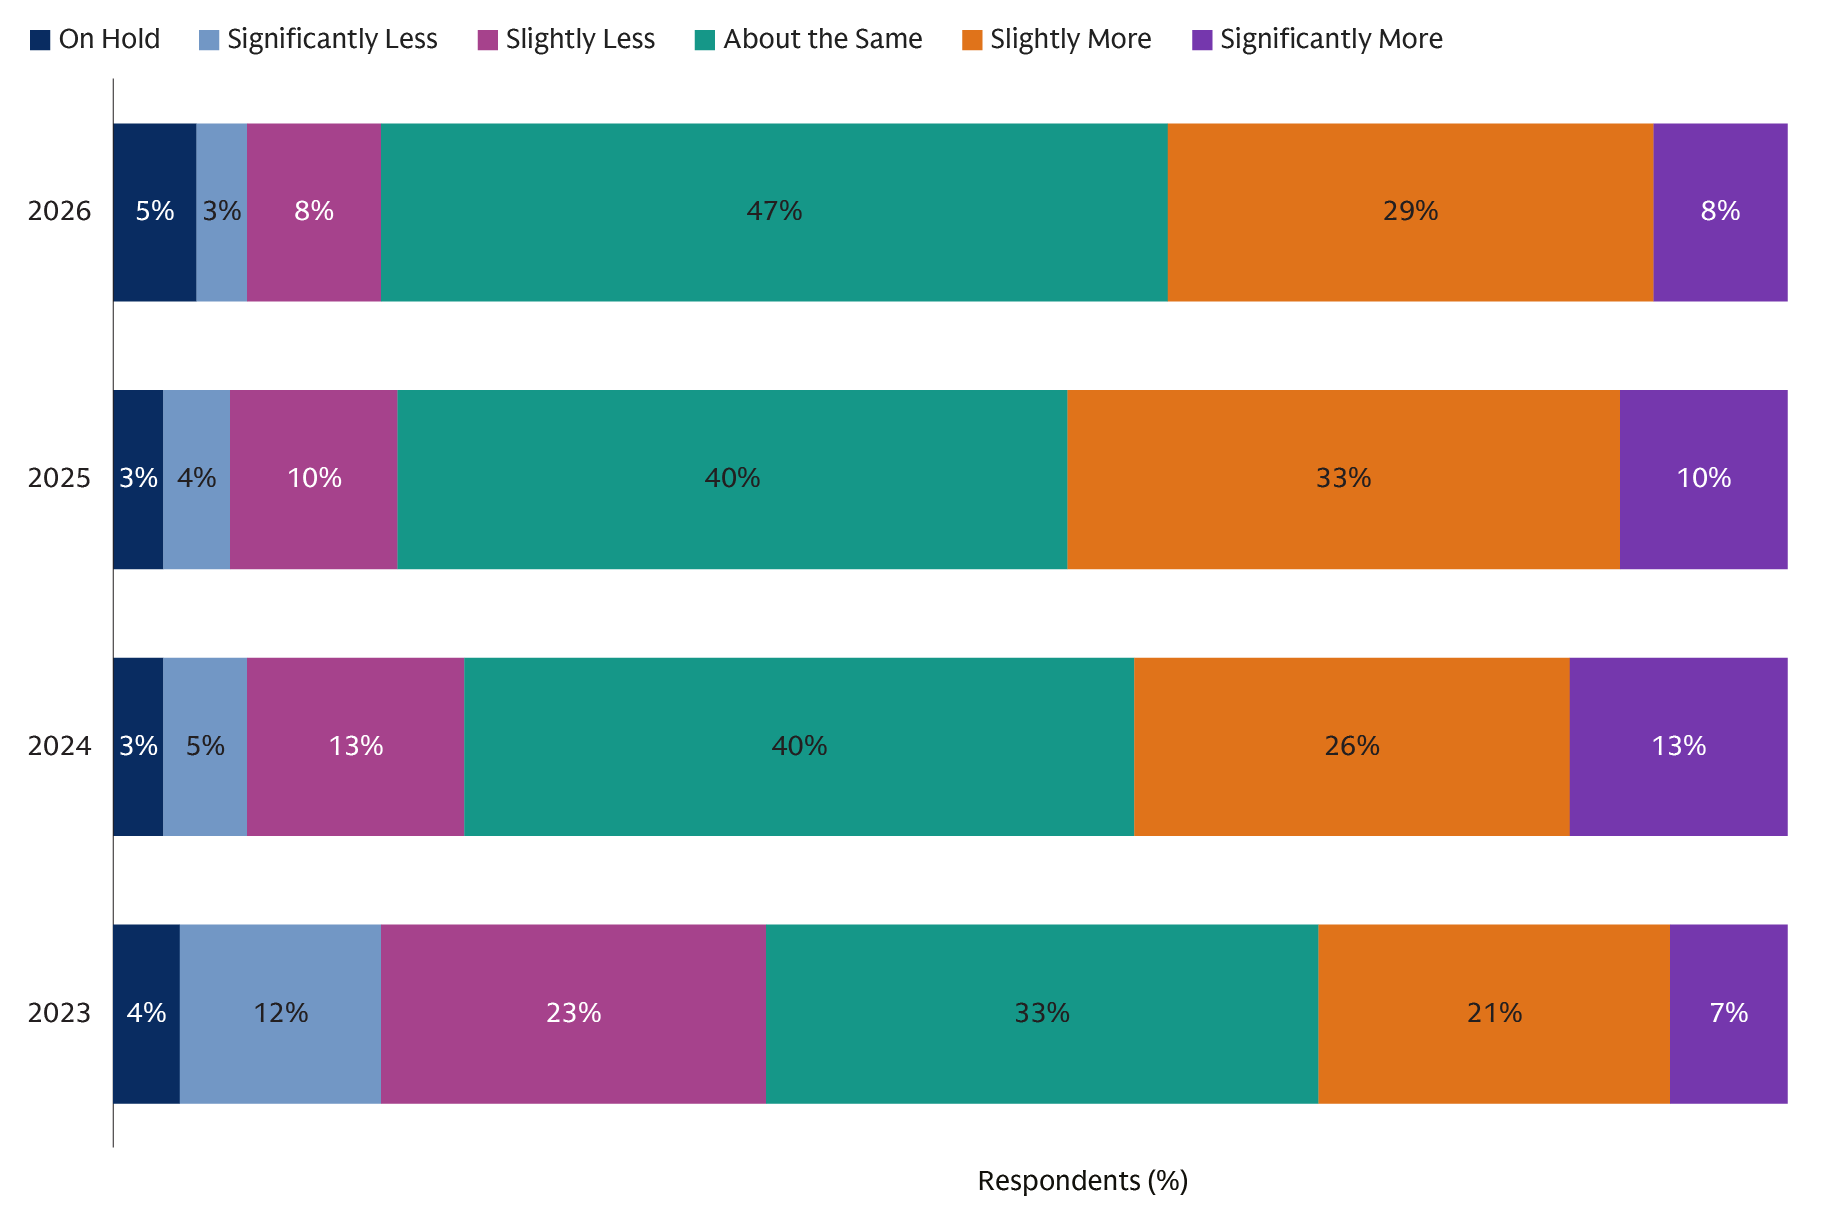
More than a third of respondents, 37%, expect to deploy more capital than last year, while 47% plan to maintain their current pace. Lack of distributions is the most frequently cited factor affecting deployment plans.
What are your expected overall capital deployment plans compared with last year?
AI is expected to reshape the alternatives industry
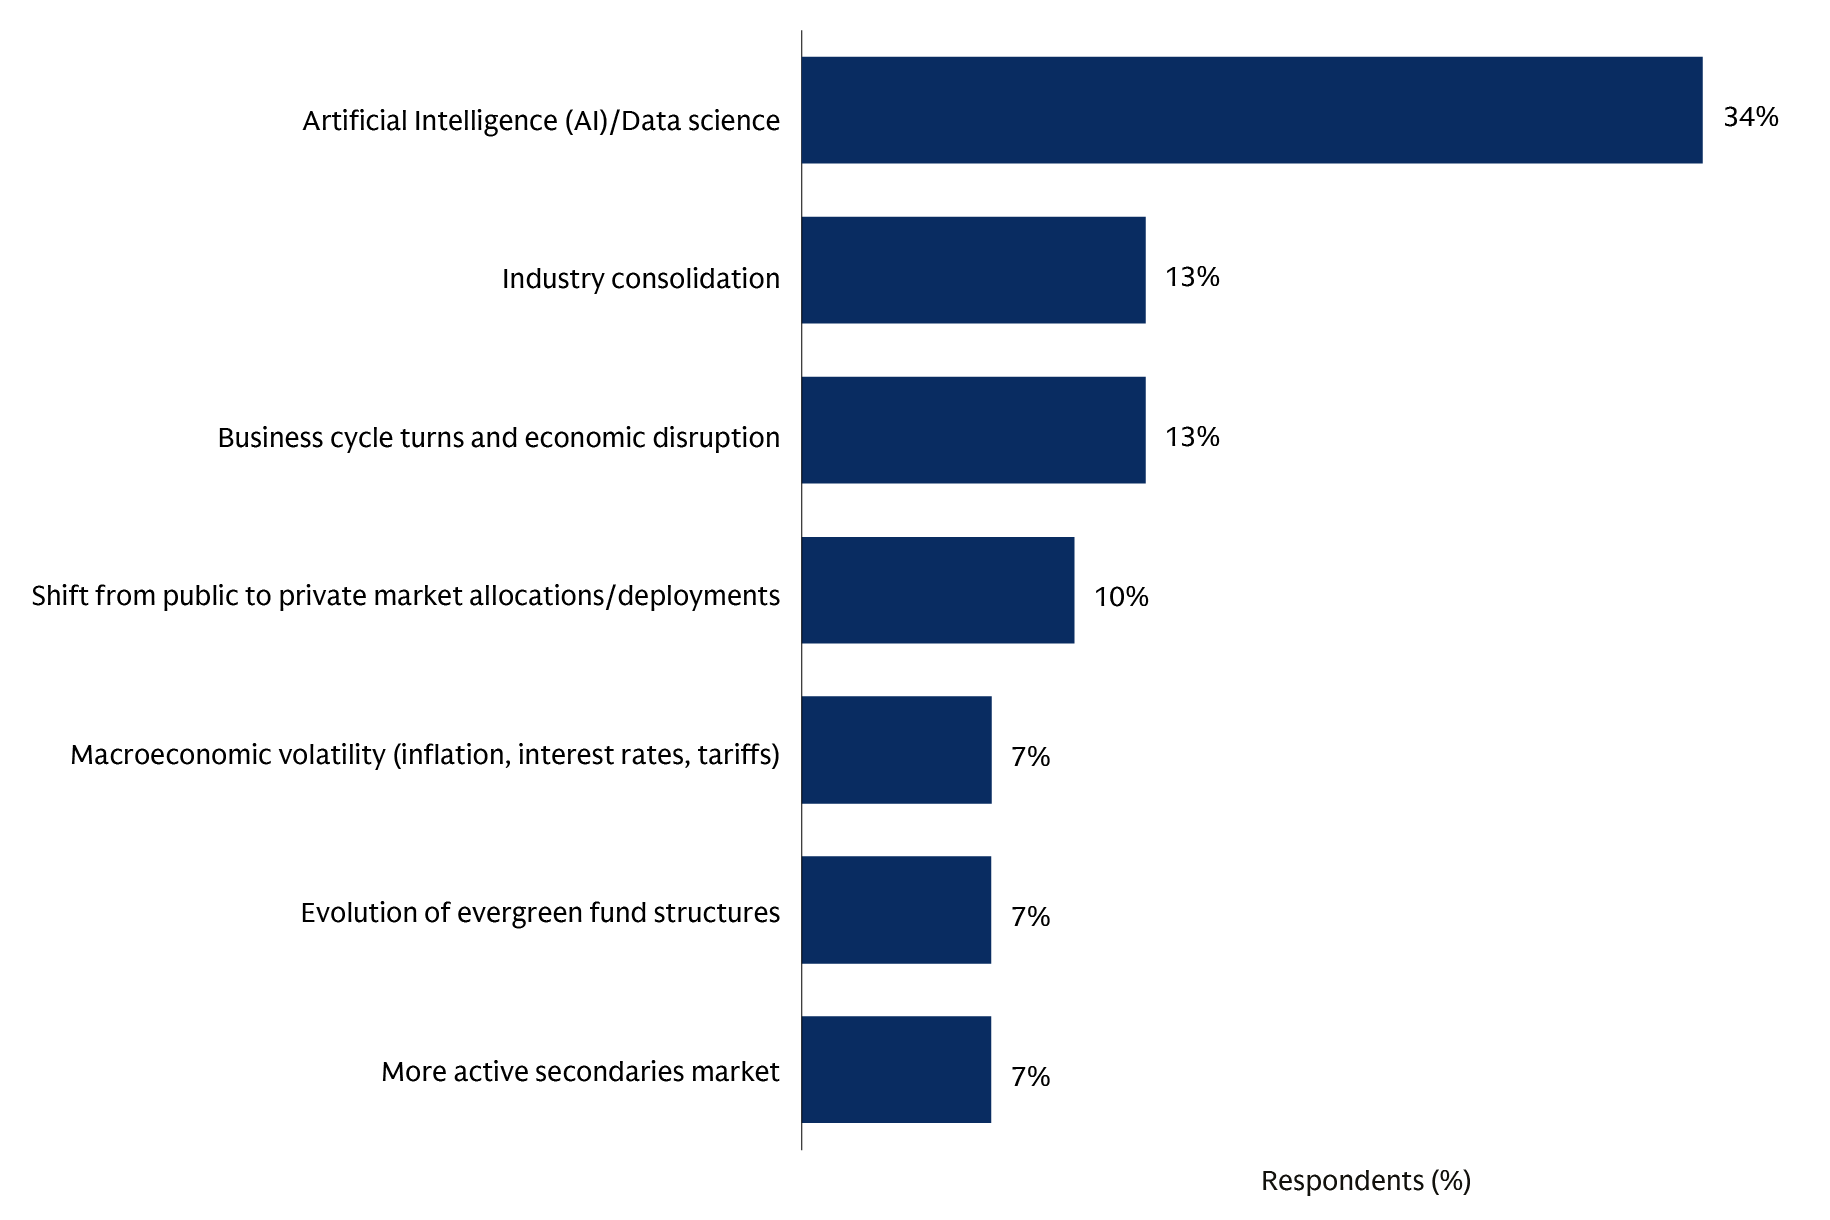
AI is expected to be the leading driver of change in the alternatives industry over the next five years, ranking ahead of industry consolidation and economic disruption. As adoption becomes more commonplace, attention is shifting toward identifying managers that can use AI to enhance investment decisions, create value across portfolio companies, and generate differentiated outcomes.
What will be the greatest driver of change in the alternatives industry over the next five years?