Learnings from Earnings
Key Takeaways
The second-quarter earnings season was one of the strongest in recent years. Adjusted S&P 500 earnings growth reached 32% year-over-year, supported by continued strength in AI infrastructure spending. Positive surprises were exceptionally broad, with more than 85% of companies exceeding earnings expectations and roughly 70% surpassing revenue forecasts.1 Strength extended beyond AI-related infrastructure beneficiaries and into consumer, industrial, infrastructure, healthcare, and technology-related end markets.
A Notably Strong Earnings Season
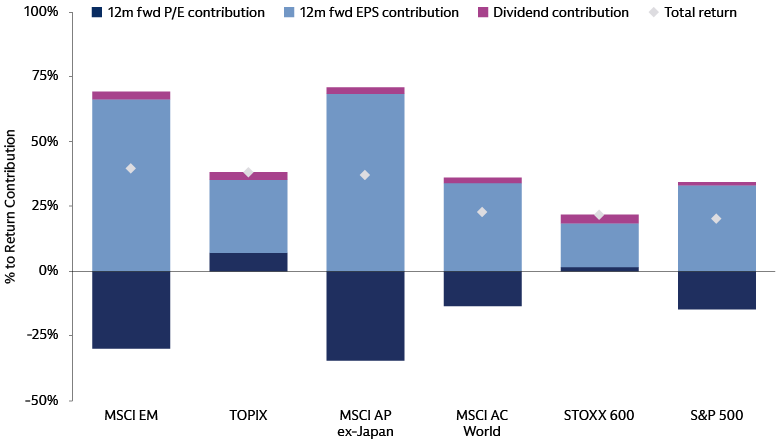
Worldwide, we have witnessed one of the strongest earnings seasons in recent history. The robustness has been rooted in fundamental earnings delivery rather than expanding market multiples, reflecting healthy corporate profitability across regions. Across major indices, returns were largely driven by earnings growth as many of these markets experienced valuation contractions over the quarter. The strongest returns over the last year have come from Japan, Asia Pacific, and emerging markets, where earnings growth, rather than valuation expansion, accounted for the majority of shareholder returns. With the cost of capital remaining structurally higher, earnings growth is increasingly becoming the primary driver of returns across markets.
Source: Factset, Datastream, STOXX, Goldman Sachs Global Investment Research. As of August 31, 2026. For illustrative purposes only.
What we believe stood out this season was not simply the magnitude of earnings growth, but its breadth. In the US, adjusted earnings growth exceeded 30%, revenue growth accelerated to its strongest pace in four years, and the vast majority of companies delivered earnings and revenue ahead of expectations. Importantly, strength extended well beyond a handful of AI beneficiaries, with healthy demand evident across consumer, industrial, infrastructure, and technology-related end markets. Management teams consistently pointed to accelerating AI investment, resilient consumer spending, improving margins, and continued investment in cloud infrastructure, power, and industrial modernization. While AI remains an important growth engine, the broader takeaway was that earnings growth is becoming increasingly widespread across sectors and geographies. As company-specific execution plays a larger role in differentiating potential winners from losers, we believe the environment is becoming increasingly favorable for active stock selection.
Execution is Driving Earnings Dispersion
We believe one of the biggest lessons from this earnings season is that execution increasingly matters more than sector exposure.
Across industries, earnings outcomes varied meaningfully among companies operating in the same markets. Product launches, pricing, capital allocation, operational discipline, and management execution repeatedly emerged as key differentiators.
Healthcare provided one of the most compelling examples. Despite negative sector earnings growth, many companies exceeded expectations through robust commercial execution, improving demand trends, and successful product adoption. Similar patterns emerged across consumer sectors, where market share gains were increasingly driven by company-specific initiatives rather than broad-based improvements in demand.
In our view, this growing dispersion reinforces a compelling backdrop for active management. As earnings outcomes become increasingly company-specific, fundamental research and stock selection may matter more than broad sector allocations. This year, we have witnessed single stock volatility far outpacing broader index volatility.
From AI Capex to AI ROI
For much of the past two years, many investors have focused on the scale of AI-related capital expenditures. This earnings season, the conversation increasingly shifted toward returns. While still early, management commentary provided growing evidence that AI investment is translating into potentially faster revenue growth, stronger customer engagement, and expanding business opportunities.
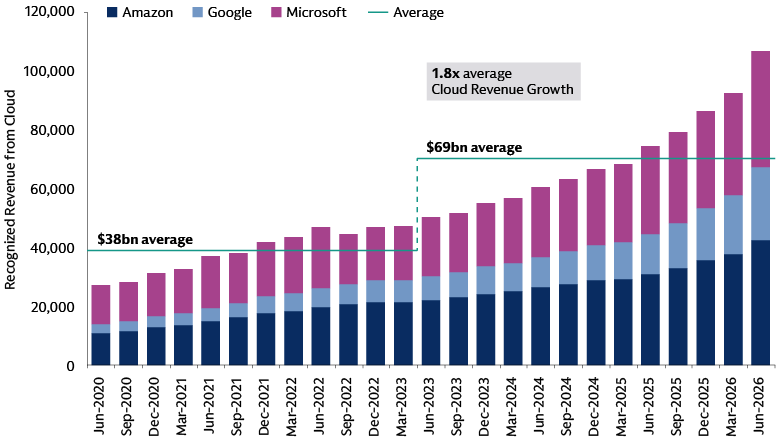
The clearest evidence came from the hyperscalers, where cloud revenue growth accelerated despite difficult comparisons. Collectively, the three largest cloud providers are generating nearly $400 billion of annualized revenue, up 43% year-over-year, supported by continued enterprise demand for AI workloads.2 Demand visibility remained strong, with meaningful backlog growth suggesting customers are making long-duration commitments to expanding AI capabilities.
Source: Company reports, Bloomberg. As of July 31, 2026. For illustrative purposes only.
Profitability remained resilient despite rising investment. Cloud margins were stable-to-higher even as capital spending increased, reinforcing confidence in the returns generated by AI infrastructure. Beyond the hyperscalers, results highlighted continued strength across the broader AI ecosystem, including cooling, power, semiconductor materials, industrial gases, and data center infrastructure.
In our view, the debate is evolving from how much companies are spending on AI to how effectively they are monetizing those investments.
As we look ahead, the key message from this earnings season is not simply that results were strong, but that earnings growth is becoming broader and increasingly company-specific. In an environment where execution, competitive positioning, and innovation are driving a larger share of performance dispersion, we believe fundamental research and active stock selection remain as important as they have been in many years.
1 Bloomberg. As of September 3, 2026.
2 Company reported, Bloomberg. As of July 31, 2026.