Market Pulse November
Macro Views
Global activity remains supported by solid corporate and household balance sheets, AI investment, and fiscal cushions, which offset the dampening effect of tighter monetary policy and higher commodity prices. We expect 2027 growth near 2% in the US, and above 1% in Europe and Japan.
The FOMC has telegraphed a pace for potential rate hikes of every other meeting. We expect them to raise rates in December, but the move in March will be highly dependent on the data. If inflation continues to normalize, with impulses from energy and tariffs rolling off, we may see them hold at 4.0-4.25%; if pressures broaden, they may have to hike. We expect the ECB to deliver one more hike in December to a peak policy rate of 2.75%.

In an election cycle, our focus is not on who wins but rather what a win may change. In the US, a divided government likely means gridlock and more of the same. Upcoming elections in Spain, France, and Italy put a spotlight on fiscal risk, with fractured parliaments less likely to address debt burdens. Government bond yields may stay elevated, as seen recently in French OATs.
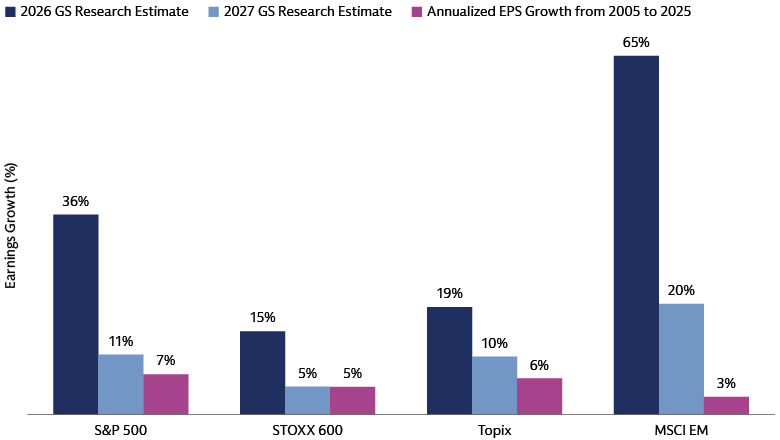
Source: Bloomberg, Goldman Sachs Global Investment Research, and Goldman Sachs Asset Management. As of October 30, 2026. Past performance does not predict future returns and does not guarantee future results, which may vary.
Market Views
Earnings growth has been exceptional in 2026, boosted by AI investment and higher energy prices. We expect this growth to decelerate in 2027, but to remain supportive of equities. Historically, markets can rally for years past peak earnings growth, though they do become more idiosyncratic. As the AI cycle continues, we would expect focus to be on value capture, quality revenues, and balance sheet strength.
Higher rates have led to scrutiny around the funding requirements for AI capex, leading to greater dispersion and spread widening across the AI complex. We remain cautious on IG tech but see scope for some near-term reversal in HY given the scale of the recent selloff. Credit fundamentals are supportive and supply is expected to slow in Q4.
Our base case is for energy prices to moderate as supply/demand normalizes and risk premium recedes. However, upside risk remains from possible re-escalation in the Middle East or a colder than expected winter. We also see upward pressure on metals such as copper, where demand from electrification, data centers, and energy security is facing constrained mine supply; and gold, where central bank demand remains robust.
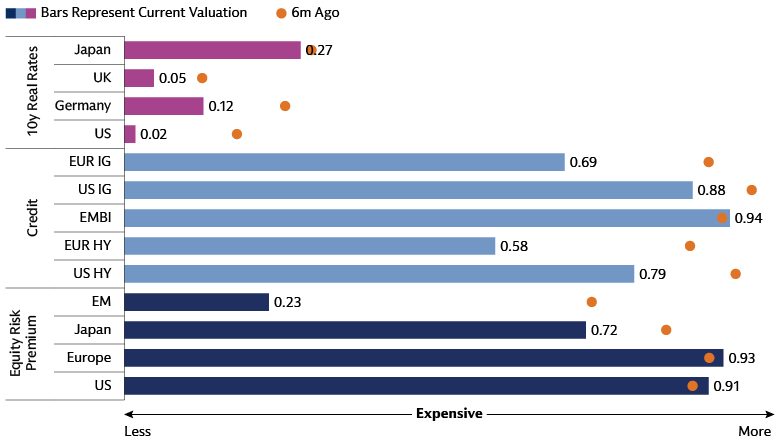
Valuations Across Assets (Historical Percentile): Source: Bloomberg, Haver, MSCI and Goldman Sachs Asset Management. As of November 1, 2026. Chart shows the Equity Risk Premium = 12M forward earnings yield (1 / Bloomberg Best 12M forward P/E) less 10Y real yield; country-specific for US/Japan, Germany for Europe and the US for EM. Credit = respective index spreads; 10Y real yields = 10Y nominal yield less 10Y breakeven inflation. Historical percentile: Monthly observations since November 2006 are used to rank each valuation metric against its historical distribution.
Going Global
Global equities have been resilient this year as strong earnings have offset energy market shocks. We think this diversification can continue to deliver in 2027 as the main themes around AI, defense, and economic security remain intact. Investor concerns about the sustainability of these trades appear to be well priced, particularly in EM where multiples are now cheaper than they have been ~90% of the time for the last 20 years.
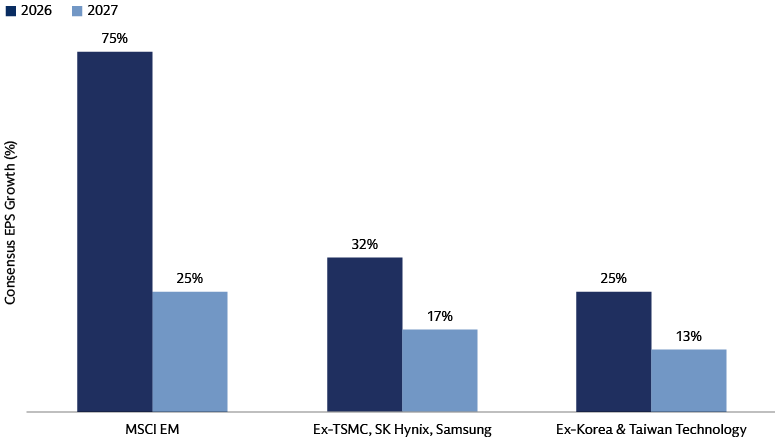
Source: Goldman Sachs Asset Management. As of September 30, 2026. EM refers to emerging markets. Chart shows earnings per share (EPS) growth for different parts of the MSCI Emerging Markets Index.
The massive investment in AI infrastructure has powered outsized earnings growth in EM, and particularly among the three main hardware providers. However, we also see strong growth potential in the specialized supply chains around AI including chip inputs, testing, packaging, and distribution. Additionally, commodity and consumer themes continue to play out across other markets, driving broad based strength across EM that investors have not seen for decades—annualized EPS growth from 2005-2025 was just 3%.
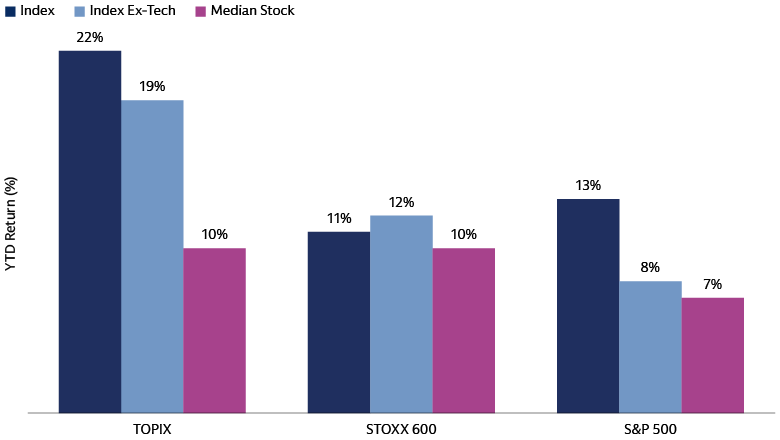
Source: Goldman Sachs Global Investment Research. As of October 30, 2026. DM refers to developed markets. Chart shows the year-to-date total return for different parts of the TOPIX, STOXX 600, and S&P 500 Indices.
Returns in Japan and Europe have also been strong beneath the surface, with the median stock beating the median in the US. We believe Europe’s strength reflects the lack of concentration in tech and the broader beneficiaries of higher rates, infrastructure spend, and energy prices, plus higher dividend yields that may help smooth volatility. Meanwhile Japan has been the beneficiary of multiple major market themes, including AI investment, defense, and infrastructure spend, and domestic fiscal impulse.
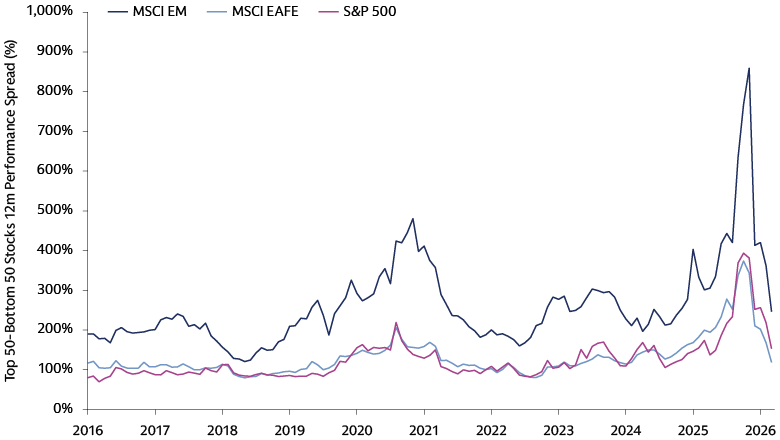
Source: Bloomberg and Goldman Sachs Asset Management. As of October 30, 2026. Chart shows the difference in returns between the top 50 stocks and the bottom 50 stocks on a rolling 12-month basis.
Dispersion has picked up across global markets this year as disruption has amplified potential winners and losers, with the difference between top and bottom performers over 400% in EM and 200% in DM. In our view, active management is always important in EM, a universe of 1,165 companies across 24 countries where geographic, sector, and security selection can add value. But even in DM, the high median stock returns and low cross-stock correlations that we see today may offer strong alpha potential.