2026 Global Alternatives Survey: The GP View
Key Findings
GPs Eyeing New Pathways to Distributions
As the overall exit environment grows more challenging, GP curiosity about non-traditional paths to returning capital is rising. More respondents say that they’re “somewhat likely” to use portfolio finance or continuation vehicles than in prior years. Yet they show a strong preference for traditional exit routes like sponsor sales and strategic sales.
To Scale, GPs Tap Trusted Sources
GPs are targeting larger flagship funds, but instead of building out new strategies or tapping new sources of capital, they’re largely drawing from traditional sources. More are offering evergreen strategies and pursuing retail capital, but drawdowns and institutional capital still dominate – unsurprising, as most of our GPs are middle-market firms.
AI Transformation Front and Center
GPs show strong enthusiasm for Artificial Intelligence (AI). Technology more broadly is the preferred tool for value creation, and about three-quarters of GPs say they’re using or considering using AI to assess investments and cut costs. Yet many have yet to fully tap AI’s potential: roughly a quarter say incorporating AI use cases is a top challenge for their organization, suggesting there’s still room to run.

Recalibration, Not Reinvention
Valuations are the biggest obstacle to exit
Nearly two-thirds (65%) of GPs ranked valuations as a top-three challenge for exit, up from 60% in 2025. Macro uncertainty came second at 50%, while concern over the cost and availability of financing has fallen sharply since 2024.
What are the greatest challenges in exiting investments today? Select up to three.
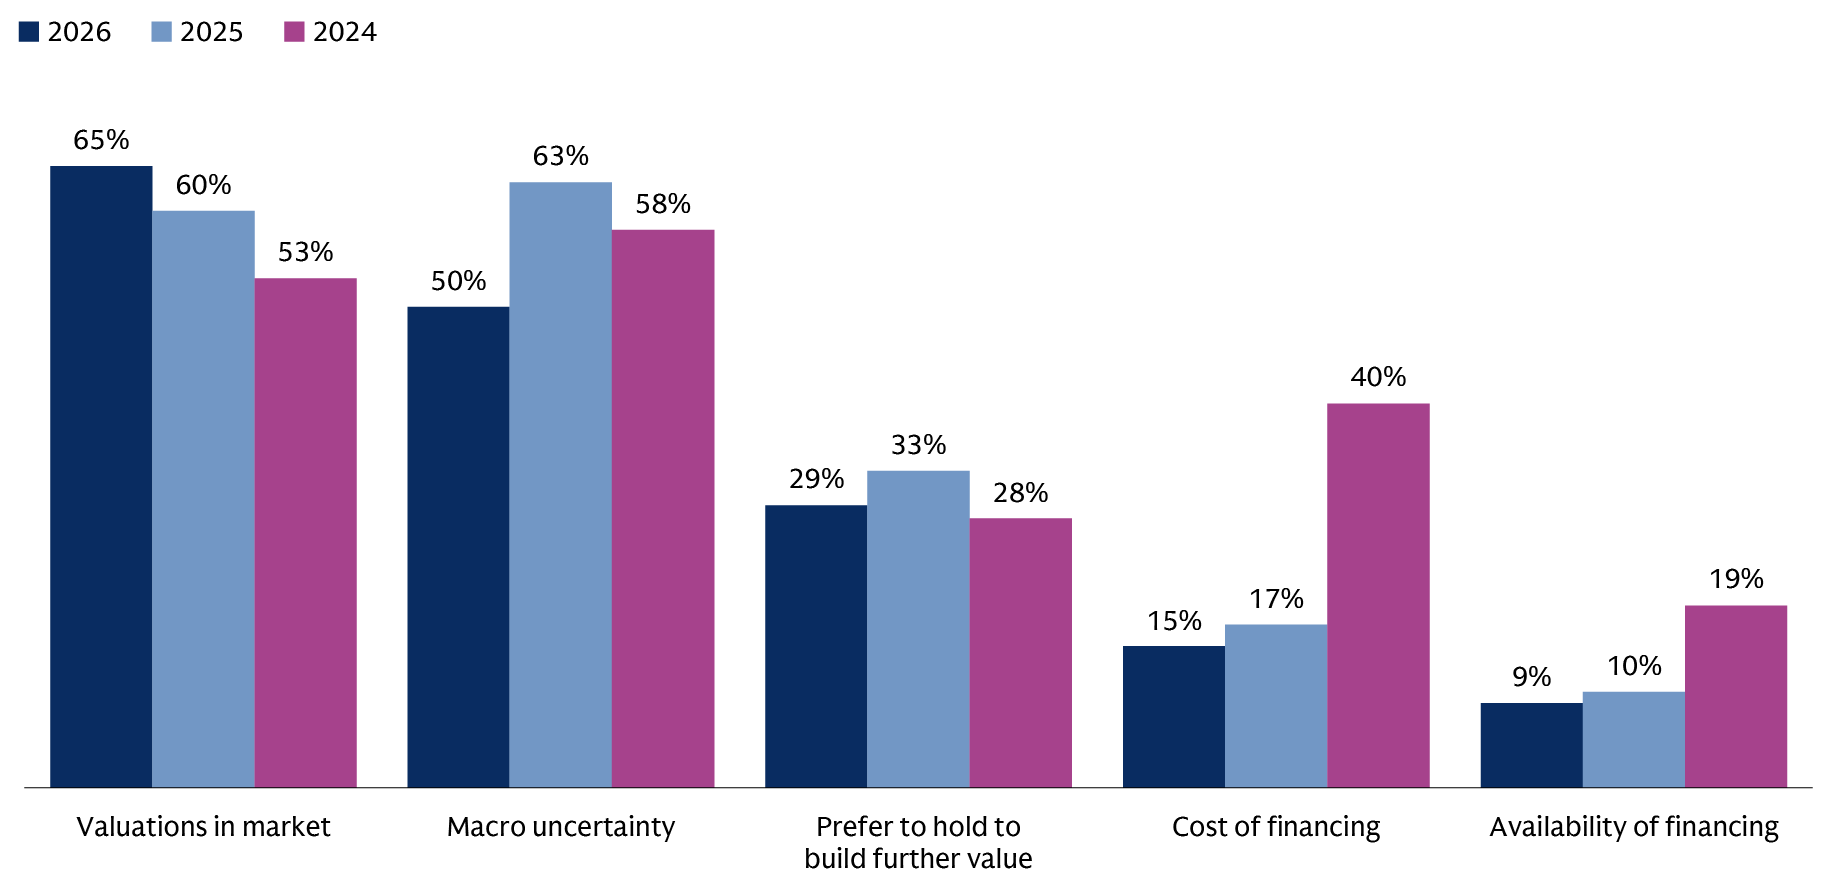
Source: Goldman Sachs Global Alternatives Survey, June–August 2026. Figures may not sum to 100 due to rounding.
Fundraising ambitions return, but traditional channels still lead
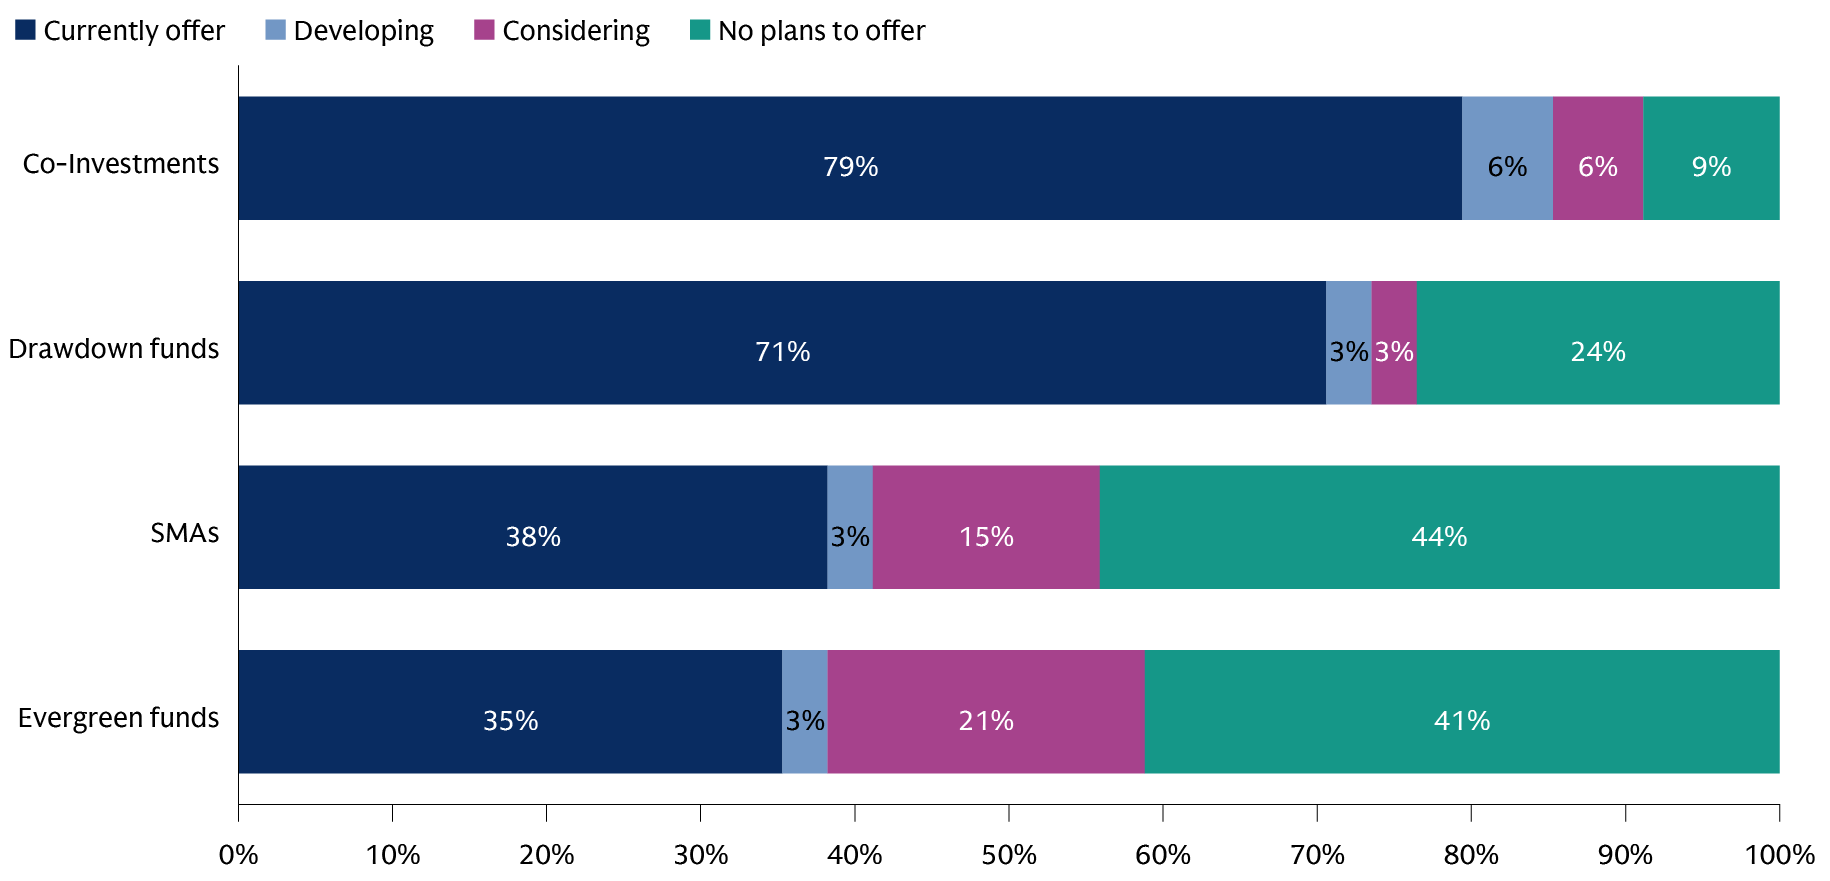
The share of GPs targeting a next flagship larger than their last rebounded to 65%, up from 52% in 2025. Yet only 35% offer evergreen strategies, versus 79% offering co-invest and 71% offering drawdown funds, and just over a third (35%) call retail a high priority.
Which fund structures and investment options does your firm offer?
AI is the top expected driver of change
Nearly half (47%) of GPs named AI the top driver of change over five years, ahead of business cycle turns (19%). Over three-quarters (77%) use or are considering AI to reduce costs, but about a quarter cite integration as a top challenge.
What will be the greatest driver of change in alternatives over the next five years?
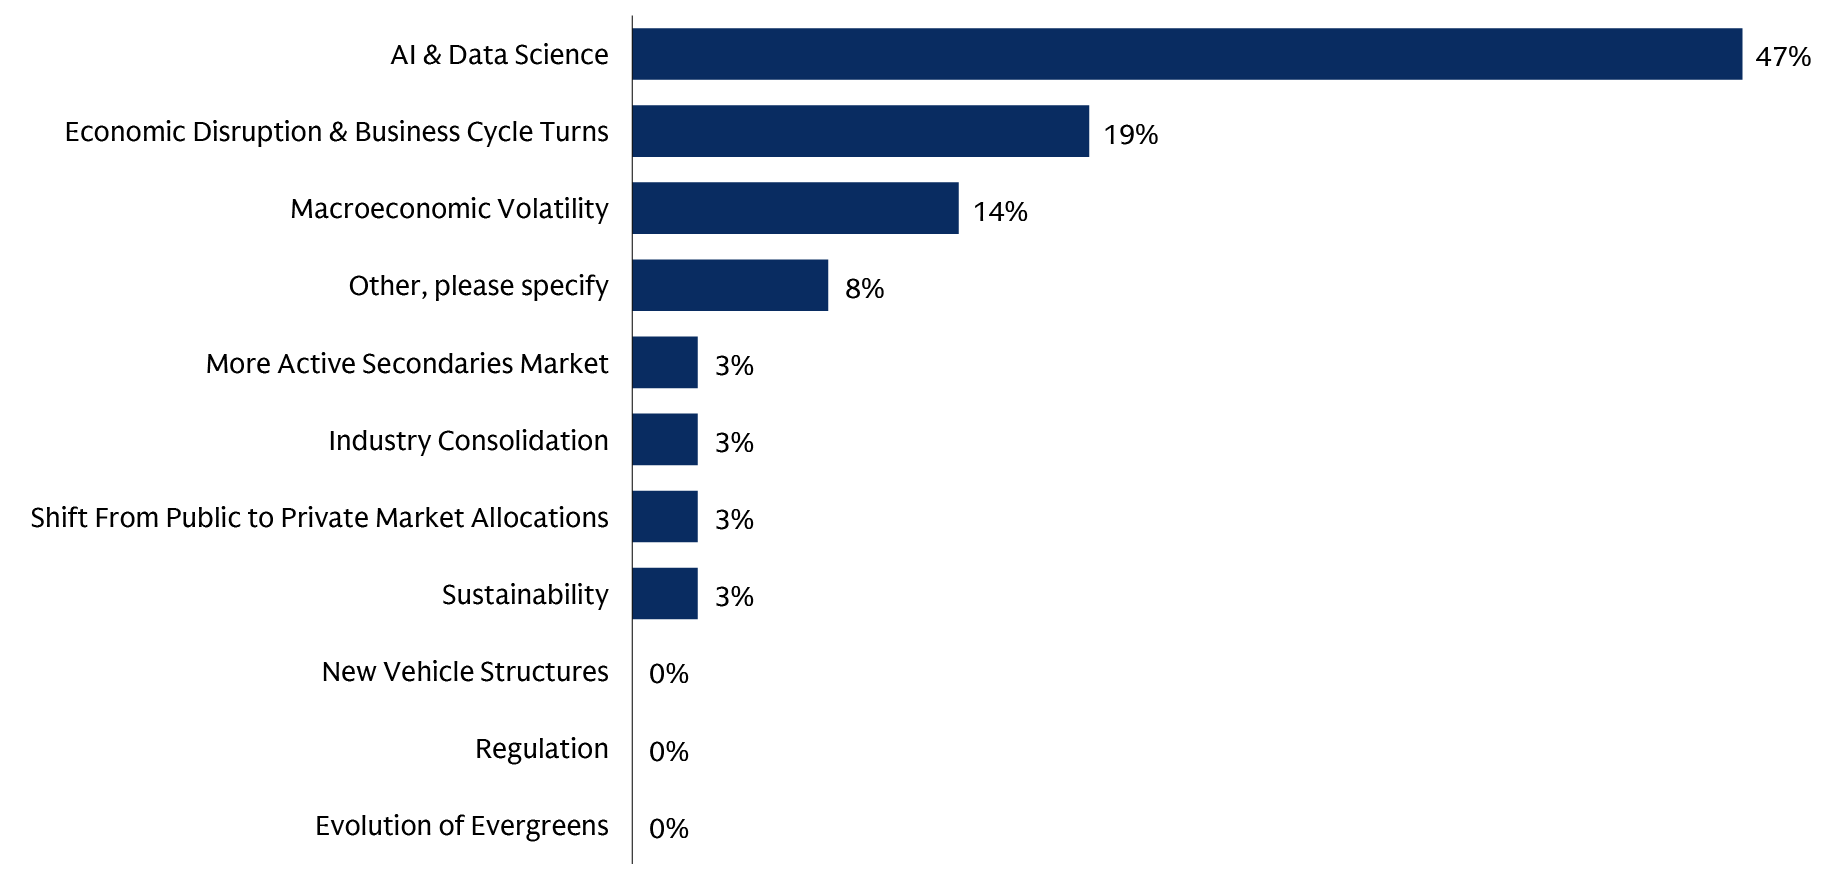
Respondents were given the option of ‘Other’. A shift to retail capital and democratization were most quoted as other drivers of change.