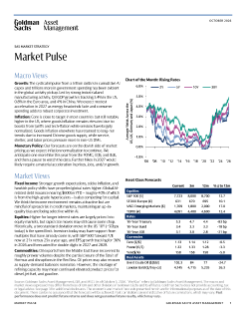
Market Pulse October


Macro Views
The cyclical impulse from a trillion dollars in cumulative AI capex and trillions more in government spending has been evident in the global activity pickup. Led by strong industrial and manufacturing activity, Q3 GDP growth is tracking 3.4% in the US, 0.8% in the Euro area, and 4% in China. We expect modest acceleration in 2027 as energy headwinds fade and consumer spending adds to robust corporate investment.
Core is close to target in most countries but still notably higher in the US, where goods inflation remains elevated due to boosts from tariffs and tech-flation while services have largely normalized. Goods inflation elsewhere has returned to long-run trends due to increased Chinese goods supply, while service, shelter, and labor prices pressure more in non-US DMs.
Our forecasts are on the dovish side of market pricing as we expect inflation normalization to continue. We anticipate one more hike this year from the FOMC, ECB, and BoE, and then a pause to watch the data. Further hikes in 2027 would likely require a material acceleration in prices, jobs, and/or growth.
Source: Bloomberg and Goldman Sachs Asset Management. As of September 30, 2026. Past performance does not predict future returns and does not guarantee future results, which may vary.
Market Views
Stronger growth expectations, sticky inflation, and hawkish policy shifts have propelled global rates higher. Global AI-related debt issuance nearing $600bn YTD – roughly 40% of which is from the high-grade hyperscalers – is also competing for capital. We think the income environment remains attractive but are mindful of spread risk in credit markets, maintaining an up-in-quality bias and being selective within AI.
Higher for longer interest rates are largely priced into equity markets, but rapid rate moves may still cause some chop. Historically, a two standard deviation move in the US 10Y (~50bps today) is the speed limit. Investors today may have support from multiples that have already come in, with S&P 500 forward P/E now at 21x versus 25x a year ago, and EPS growth tracking for 36% in 2026 and forecasted for double digits in 2027 and 2028.
Oil exports from the Middle East have recovered to roughly prewar volumes despite the partial closure of the Strait of Hormuz and disruptions in the Red Sea. Oil prices may also recover as supply-demand balances normalize. However, the shortage of refining capacity may mean continued elevated product prices for diesel, jet fuel, and gasoline.
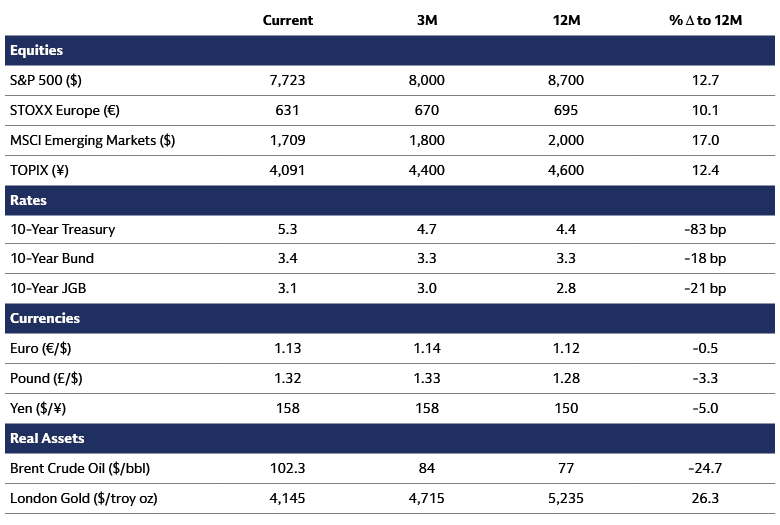
Asset Class Forecasts: Price targets of major asset classes are provided by Goldman Sachs Global Investment Research. As of October 5, 2026.
Harvest Yield
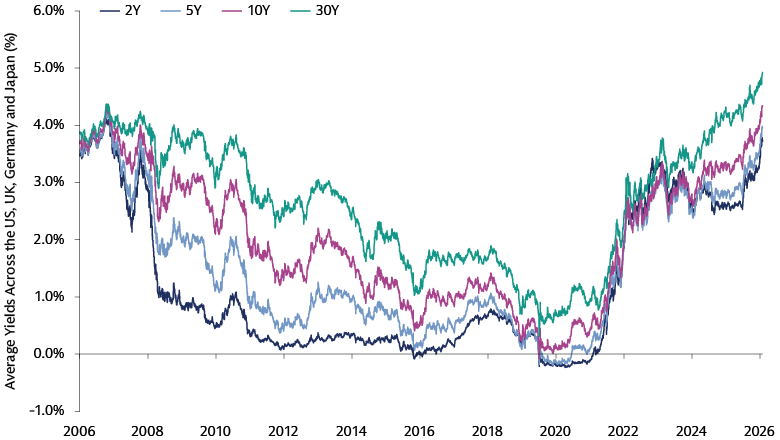
Global bond yields have risen sharply, driven by stronger nominal growth, lingering inflation, fiscal concerns, and increased competition for capital from AI. Yields sit at attractive levels, though a sustained rally may require lower energy prices or slower growth. We believe investors should prioritize carry (the income received for holding a bond) and favor areas of the market that may offer the most attractive yields relative to their risks. Given that starting yields are the strongest predictor of future returns, we think higher rates can offer attractive potential for fixed income investors today.
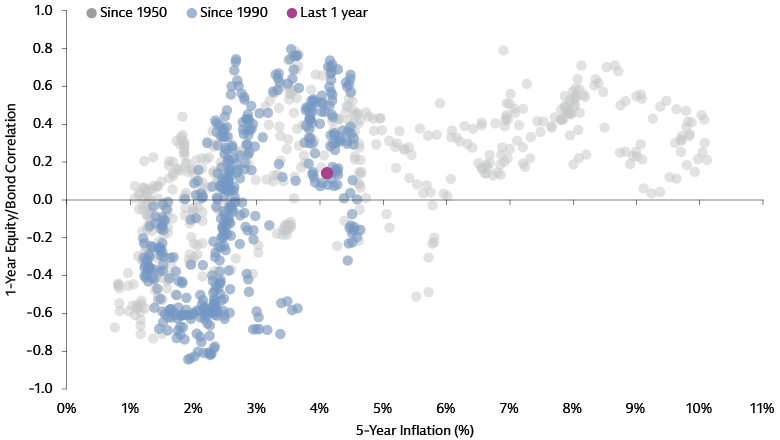
Source: Goldman Sachs Global Investment Research. As of July 31, 2026. Chart shows the relationship between equity and bond prices based on different inflation regimes. A correlation closer to 1 implies a stronger relationship, a correlation closer to 0 implies a smaller relationship.
The role that bonds play in a portfolio depends in large part on the rate of inflation. Historically, equity/bond correlations are more positive in inflationary environments, limiting their hedging potential – as we have seen post-covid and in reflationary regimes of the past. Going forward, we think continued disinflation can make correlations less positive, but bonds may increasingly be more of a tool for income generation rather than risk mitigation.
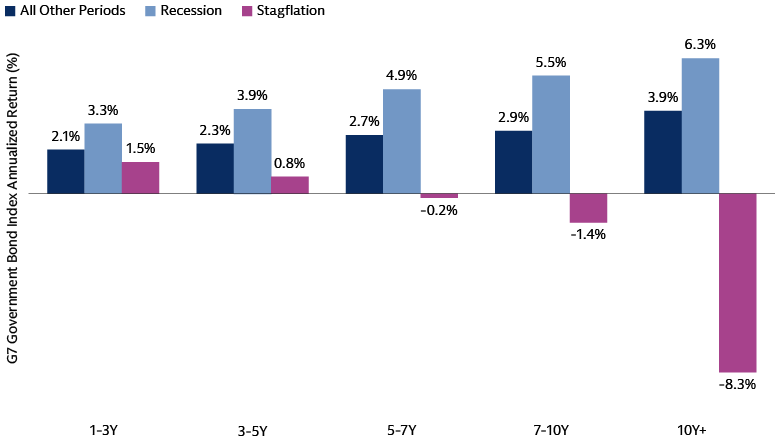
Source: Macrobond Goldman Sachs Asset Management. As of September 30, 2026. Chart shows global bond performance in different environments. Recession refers to when G7 CPI is <2.5% and G7 composite PMI is <48. Stagflation refers to when G7 CPI is >3.5% and G7 composite PMI is <50. G7 refers to Canada, France, Germany, Italy, Japan, United Kingdom, and United States.
Markets have faced both growth and inflation risks this year, leading to rapid repricing of curves around the world. We believe dynamic bond strategies that can actively adjust duration, sector, and/or regional exposure are well poised to navigate uncertainty and capture potential opportunities across changing market conditions. Given the balance of risks today, the front of the curve appears to be the best all-purpose option for rates moving higher, lower, or holding steady.
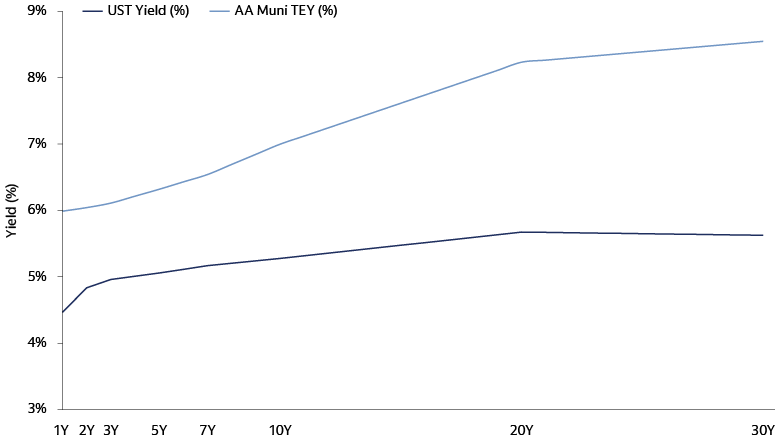
Source: Bloomberg and Goldman Sachs Asset Management. As of September 30, 2026. Chart shows the tax-equivalent yield (TEY) curves for US Treasury bonds and AA municipal bonds at a tax rate of 37%.
Municipal bonds may offer attractive tax-equivalent yields and steeper curves relative to Treasuries. We believe a focus on income and active yield curve positioning may help muni investors navigate potential volatility. SMAs may offer structural advantages given customization, tax-loss harvesting, and the potential downside protection of owning bonds to maturity. Elevated supply and headline-driven volatility may remain, but a resilient economy and healthy reserve balances continue to put municipalities in a strong position in our view.